All politics isn’t local
You can subscribe to receive these notes by email here
The geopolitical aftershocks of Russia’s invasion of Ukraine continue. The invasion and the Western-led response are accelerating the emergence of a more fragmented global economy, in which global trade and investment flows are shaped by shared political values and interests – values-based globalisation, or what Janet Yellen recently called ‘friend-shoring’.
But alongside intense geopolitical developments, recent events suggest elevated domestic political risks in countries from China to the US that could impact on the global outlook.
Political incentives may be local, but in a deeply connected world the consequences are not. Particularly in autocratic regimes with limited checks and balances, radical decisions can be made quickly – from the invasion of Ukraine to China’s Covid lockdowns – and with far-reaching implications. And democracies, notably the US, are under strain – creating exposures for the rest of the world. Political risks in systemically important countries are sitting at highly elevated levels.
A closed China
With the possible exception of Russia, China is the biggest single location of near-term domestic political risk. President Xi, who plans to secure a third term at the Party meetings in November, is presiding over draconian lockdown policies in Shanghai (and elsewhere) in pursuit of China’s zero-Covid policy.
But the contagious nature of Omicron, a low vaccination rate among the elderly, and ineffective Chinese vaccines (and a refusal to administer more effective western vaccines) have put Chinese authorities in a bind. The rigid lockdowns are exerting substantial economic and social costs on the population – with no clear end-point – and are also creating mounting political risks for the leadership.
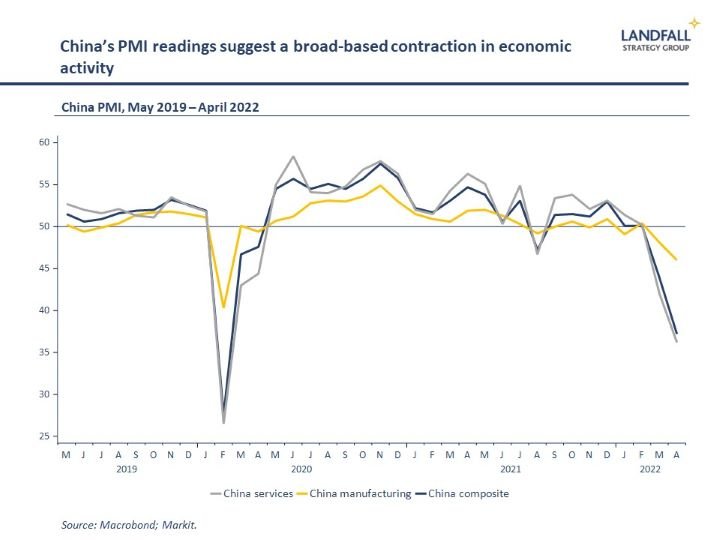
The risk is less of regime change or mass political protest in China – or even of Mr Xi not securing a third term – but of increasingly repressive, inward-looking policies (Hong Kong’s experience is cautionary). The Chinese economy is softening; and it was already in weak shape prior to the recent lockdowns partly because of a series of political decisions on the technology and property sectors. Things could get worse, despite recent macro stimulus measures.
The potential for poor political decision-making in Beijing has clear spillovers into the global economy: weaker demand, disrupted global supply chains, and so on. And the political incentives facing the CCP seem to be for a more closed stance, reinforcing China’s inward turn.
This closed, autocratic system of decision-making, with highly concentrated personal rule, has clear parallels to Russian decision-making. This led to the strategic disaster of the invasion of Ukraine; and could similarly lead China into poor choices. An invasion of Taiwan, still a priority for Mr Xi, is unlikely in the near term (and is even less likely after the Russian invasion), but the probability is not zero in this decision-making environment.
China is the largest political risk in the world, because of this highly centralised decision-making. There is enormous key person risk at the heart of the global economic and political system.
Shining light on the hill?
The second location of systemically important domestic political risk is the US. Recent disclosures about the attempted coup after the last Presidential election, and the response to this week’s leaked Supreme Court draft judgement on abortion rights, remind how deeply divided the US is.
The US has staged the strongest post-Covid recovery of any large advanced economy. And Warren Buffet famously warned never to bet against America. That has been sound advice over time. The challenge is to figure out when political dysfunction overtakes the economic dynamism of the US. It hasn’t so far, but there are growing concerns.
These political dysfunctions mean that the US is able to do little at federal level beyond fiscal stimulus. This will be worsened if the Democrats lose Congress in the November mid-terms, as is likely. And a Trump (or Trump surrogate) victory in 2024 would likely mean a return to the chaos of the Trump Administration with its erratic decision-making and degrading of norms and institutions.
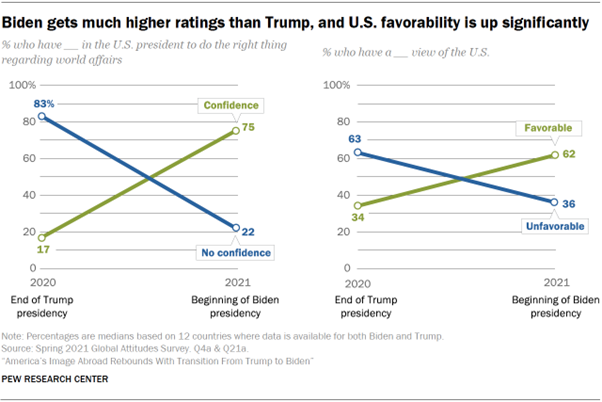
These political risks have international implications. Mr Biden has handled Ukraine in a very different way than Mr Trump would have. And another Trump-like Administration would likely not be inclined to work with coalitions of other countries; from NATO to groupings like the Quad in Asia. For all of Dr Yellen’s talk of friend-shoring, many in Europe and Asia are not sure how friendly a Trump-like Presidency would be. EU/US relations are strong at the moment, but there is doubt that this will last – which strengthens the case for European strategic autonomy.
Elsewhere
Political risks also lurk in Europe. Populist parties haven’t gone away, with persistently high vote shares in several European countries. Rising interest rates could cause economic and political stress in southern European countries, from Greece to Italy, that still have high debt loads. And Brexit continues to impose costs on the UK – and the low-quality UK government has little capability to make the best of the post-Brexit environment.
Higher rates of inflation are causing political stress around the world, particularly higher food and energy prices. Households are being squeezed, and wage growth is generally not keeping pace with the cost of living. The distributive impacts of higher inflation make it a potent destabilising force in politics.
It is not all bad news. President Macron comfortably won re-election over Ms Le Pen (and is inaugurated tomorrow) on a policy platform that was effectively a choice between an open or closed French policy stance. And from Italy to Germany and the Netherlands, the political centre is still holding.
More broadly though, there are higher levels of political risk worldwide. On a GDP-weighted basis, levels of democratic strength have been reducing over time with larger amounts of global GDP controlled by a handful of leaders in autocratic systems (see the Economist chart below). I have described this weakening of institutional strength, and the accompanying increase in political risk, as ‘the world as an emerging market’.
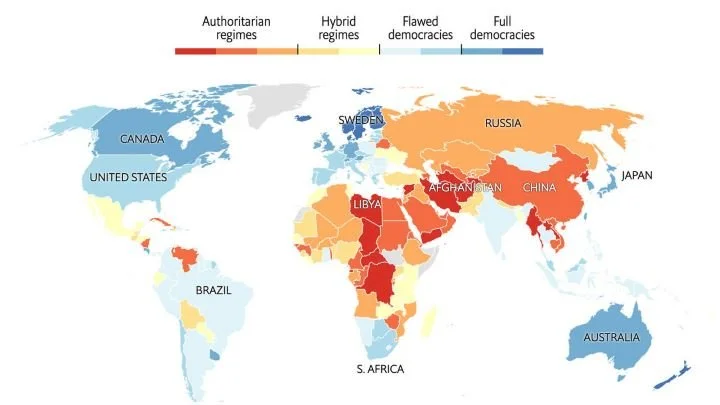
Autocracies can deliver good outcomes for a time, but they are less good at sustaining performance. At best, there is a mixed economic record in countries from Turkey (inflation rates of 70% reported this week) to Brazil and Hungary. The distribution of possible outcomes is much higher in autocratic regimes.
Prepare for events
Just as geopolitical risk assessments changed quickly after Russia’s invasion (which was not the consensus view on February 23), so too firms, investors, and governments should prepare for disruptive changes in domestic politics. Recent experience shows how quickly certainties can change: the Brexit vote and Mr Trump’s electoral win in 2016, were both unexpected – and dramatically changed the global risk landscape, upending markets and corporate strategy.
'Events, dear boy, events', UK Prime Minister Harold Macmillan on the greatest challenge for a political leader
The way in which geopolitical developments play out (decoupling, friend-shoring) will depend importantly on domestic political dynamics in China, the US, and elsewhere. For example, China looks likely to continue to turn inwards, and there are risks around the sustainability of the US commitment to values-based coalitions of countries that have been developing.
The heightened potential for disruptive political events and actions in key economies matter for these economies directly, as well as for those exposed to the global economic and political system (which is to say, almost everyone – and particularly small economies). Domestic politics can’t stay local.
If you are not subscribed yet and would like to receive these small world notes directly in your inbox, you can subscribe by clicking on the button below:
I provide advisory services and deliver presentations on global economic, policy, and geopolitical issues, for policymakers, firms, and investors. Do get in touch if you would like to discuss these services.
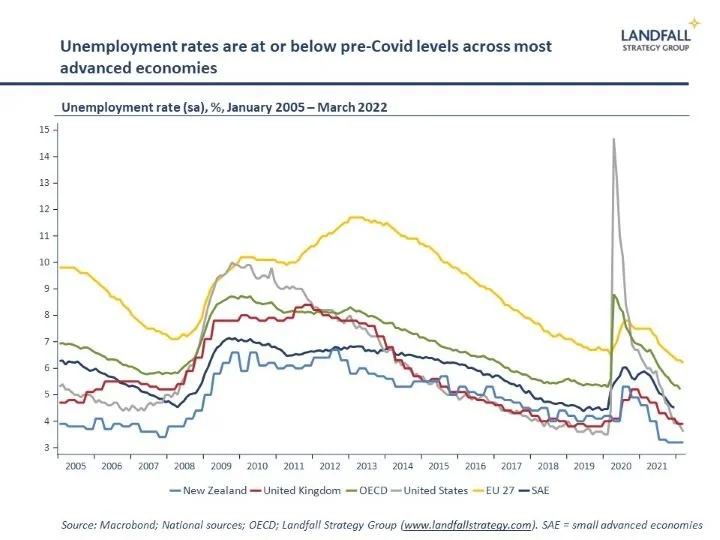
Chart of the week
Despite a slowing global economic recovery, labour markets remain very tight across advanced economies. Unemployment rates are at or below their pre-Covid levels in the EU, the US, New Zealand, and elsewhere. Firms around the world report that labour shortages are increasingly a binding constraint on output growth – although wage growth remains negative in real terms in many advanced economies.
Dr David Skilling
Director, Landfall Strategy Group
www.landfallstrategy.com
www.twitter.com/dskilling